Read the full context, compare alternatives and consider your own circumstances before making a financial decision.
You want to start investing, but you don’t have ₹1 lakh or ₹5 lakh available today.
You may have ₹500, ₹1,000 or ₹5,000 that you can comfortably set aside every month.
Can such relatively small amounts really help you build wealth over time?
That’s the basic idea behind a Systematic Investment Plan, better known as a SIP.
A SIP allows you to invest a fixed amount in a mutual fund scheme at regular intervals instead of waiting until you have a large lump sum. AMFI describes SIP as an investment methodology through which investors can put a fixed amount into a mutual fund scheme periodically.
But SIP is often misunderstood.
A SIP is not an investment product by itself. It is simply a method of investing in a mutual fund.
Understanding that distinction is the first step towards using SIPs sensibly.
SIP at a Glance
| Question | Simple answer |
|---|---|
| What does SIP stand for? | Systematic Investment Plan |
| Is SIP a separate investment? | No |
| Where does the money go? | Into your chosen mutual fund scheme |
| How often can you invest? | Usually at regular intervals such as monthly |
| Can beginners use SIPs? | Yes, subject to understanding the fund and its risks |
| Are SIP returns guaranteed? | No |
| Does SIP eliminate market risk? | No |
| Can the investment value fall? | Yes |
| Main advantage | Disciplined, regular investing |
| Suitable period | Depends on the scheme and your financial goal |
The most important point is this:
SIP tells you how you invest. The mutual fund scheme determines where your money is invested and what risks you take.
What Is a SIP?
A Systematic Investment Plan is a facility through which you invest a predetermined amount into a mutual fund scheme at regular intervals.
For example, you might choose to invest:
₹2,000 every month
into a particular mutual fund.
Instead of manually making the investment each month, a mandate can generally be established so that the scheduled amount is automatically debited and invested.
AMFI notes that SIPs can be facilitated through mechanisms such as bank mandates and other supported payment arrangements, depending on the AMC and platform.
Think of it as creating an investment routine.
Instead of asking yourself every month:
“Should I invest now?”
you establish the amount, scheme and schedule beforehand.
How Does SIP Work?
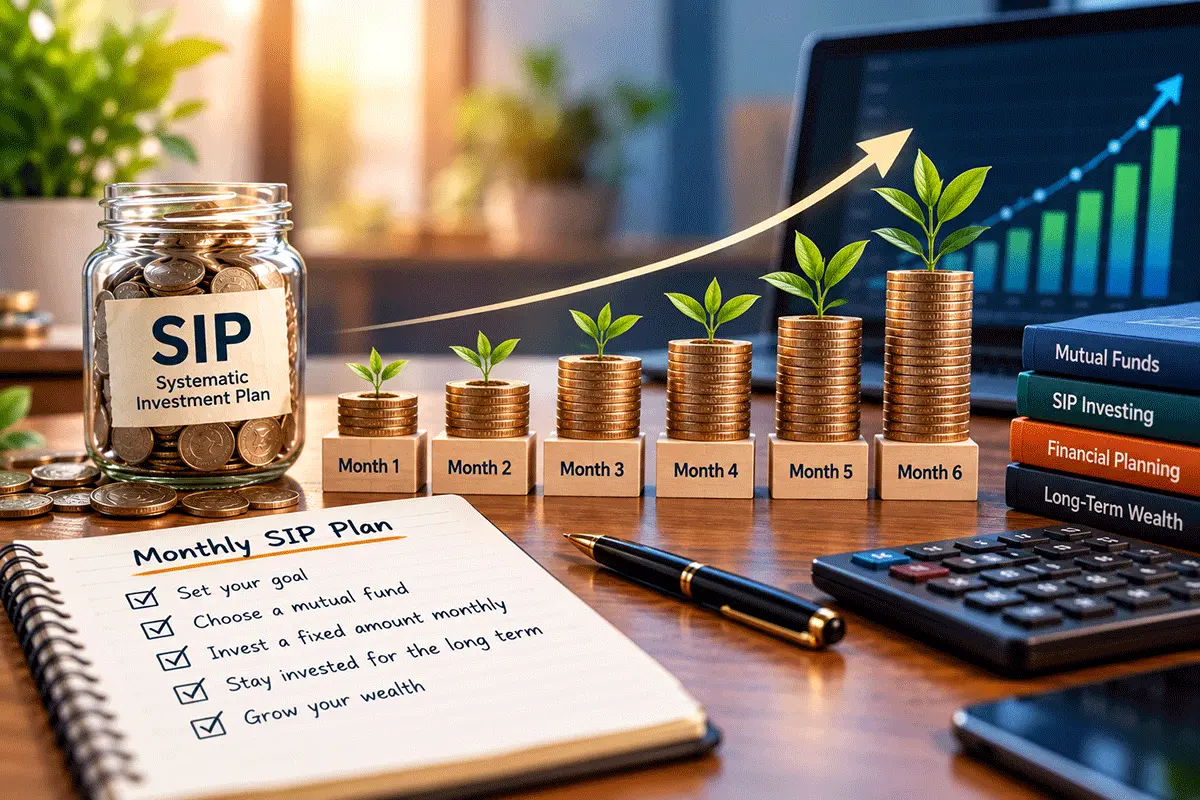
Suppose you decide to invest ₹2,000 per month through SIP.
Your journey could look something like this:
| Month | SIP amount | Total invested |
|---|---|---|
| January | ₹2,000 | ₹2,000 |
| February | ₹2,000 | ₹4,000 |
| March | ₹2,000 | ₹6,000 |
| April | ₹2,000 | ₹8,000 |
| May | ₹2,000 | ₹10,000 |
| June | ₹2,000 | ₹12,000 |
After 12 months, you would have invested:
₹24,000
After five years, ignoring changes to the SIP amount:
₹1,20,000
After ten years:
₹2,40,000
But the value of your investment will not necessarily equal the amount invested.
Why?
Because you’re purchasing units of a mutual fund, and the value of those units changes.
That brings us to NAV.
What Is NAV?
NAV stands for Net Asset Value.
In simple terms, it represents the per-unit value of a mutual fund scheme.
SEBI describes NAV as the per-unit market value of the securities held by a mutual fund after accounting for its liabilities.
Suppose you invest ₹1,000.
If the applicable NAV is ₹20:
₹1,000 ÷ ₹20 = 50 units
If on another SIP date the NAV is ₹25:
₹1,000 ÷ ₹25 = 40 units
And if the NAV falls to ₹10:
₹1,000 ÷ ₹10 = 100 units
This means your fixed SIP amount purchases a different number of units at different NAVs.
What Is Rupee Cost Averaging?
One of the most frequently discussed benefits of SIP investing is rupee cost averaging.
Because you’re investing a fixed rupee amount regularly:
- When NAV is higher, your money buys fewer units.
- When NAV is lower, your money buys more units.
AMFI explains this as rupee cost averaging—the process of regularly investing fixed amounts so that more units tend to be purchased at lower prices and fewer at higher prices.
Consider this simplified illustration:
| Month | SIP | NAV | Units purchased |
|---|---|---|---|
| Month 1 | ₹1,000 | ₹20 | 50 |
| Month 2 | ₹1,000 | ₹25 | 40 |
| Month 3 | ₹1,000 | ₹10 | 100 |
| Total | ₹3,000 | — | 190 |
You didn’t have to predict which month would have the lowest NAV.
You simply continued investing.
However, this needs an important warning:
Rupee cost averaging does not guarantee a profit and does not protect you against investment losses. AMFI’s investor material explicitly makes this distinction.
SIP Does Not Mean Guaranteed Returns
This is one of the most important things for a beginner to understand.
A bank recurring deposit and a mutual fund SIP can both involve putting aside money every month, but they are not the same type of investment.
With a mutual fund SIP, your money is invested in the underlying assets of the selected mutual fund scheme.
Depending on the fund, those assets might include:
- Equity shares
- Bonds and other debt securities
- Government securities
- Money-market instruments
- A combination of asset classes
SEBI explains that mutual funds pool investors’ money and invest it in portfolios of securities according to the scheme’s stated objective.
The investment value can therefore rise or fall.
A SIP doesn’t remove this risk.
SIP vs Lump Sum: What’s the Difference?
Both are ways of investing in mutual funds.
Lump-sum investing
You invest a larger amount at once.
For example:
₹1,20,000 today
SIP investing
You spread investments over time.
For example:
₹10,000 per month for 12 months
Total invested:
₹1,20,000
The total contribution may be identical, but the timing of investment is very different.
Neither method is automatically superior in every situation.
The appropriate approach can depend on:
- Whether you already have money available
- Your cash flow
- Market exposure
- Financial goals
- Risk tolerance
- Investment horizon
For salaried people or anyone receiving regular monthly income, SIPs can be particularly convenient because investments can align with monthly cash flow.
Why Do People Invest Through SIP?
1. You Can Start Without a Large Lump Sum
You don’t necessarily need lakhs of rupees before you can begin investing.
AMFI currently states that SIP instalments can be as low as ₹500 per month, with ₹250 per month under Chhoti SIP. Actual minimums and conditions can vary by scheme.
That makes regular investing accessible to people who are still building their financial base.
2. SIP Encourages Financial Discipline
Consider two approaches.
Approach A
“I’ll invest whatever is left at the end of the month.”
Approach B
“₹3,000 is allocated to my investment every month.”
Approach B turns investing into a planned financial commitment rather than something you do only when convenient.
Over long periods, this behavioural advantage can be important.
3. You Don’t Have to Constantly Time the Market
Trying to identify the perfect day to invest is extremely difficult.
Markets rise.
Markets fall.
News changes.
Investor sentiment changes.
With a regular SIP, you’re following a predetermined schedule rather than continually deciding whether today’s market level is “right.”
That doesn’t guarantee better returns, but it can reduce dependence on repeated market-timing decisions.
What About Compounding?
You’ll often hear SIPs associated with the power of compounding.
But we should be precise.
A SIP itself doesn’t magically generate compound returns.
Compounding occurs when gains generated by an investment remain invested and can themselves participate in future growth.
Over long periods, this can become powerful.
Consider a purely illustrative example:
Suppose you invest:
₹5,000 per month
for:
10 years
Total amount contributed:
₹6,00,000
If we assume an illustrative annualised return of 10%, the final value would be approximately:
₹10.3 lakh
Extend the same monthly contribution to 20 years, using the same hypothetical 10% assumption:
Total contributions:
₹12,00,000
Illustrative value:
approximately ₹38 lakh
These figures are examples—not predictions.
Actual mutual fund returns are market-linked and can be substantially higher or lower, including negative over some periods.
The lesson isn’t:
“A SIP will give you 10%.”
The lesson is:
Time can have a major effect when investment returns remain invested.
Starting Earlier Can Matter More Than Starting Bigger
Consider two hypothetical investors.
Investor A
Starts at age 25 and invests:
₹3,000 per month
Investor B
Waits until age 35 and then starts investing:
₹3,000 per month
Even though their monthly SIP amount is identical, Investor A has ten additional years during which invested capital can potentially grow.
This is why a manageable SIP started earlier can sometimes be more useful than endlessly waiting until you can afford a much larger monthly investment.
But affordability comes first.
Don’t start a large SIP that forces you to stop after three months.
A smaller sustainable amount can be more practical.
How Much Should You Invest in SIP?
There is no universal “correct SIP amount.”
₹500 may be meaningful for one person.
₹20,000 may be appropriate for another.
Instead of asking:
“What SIP amount gives the best returns?”
ask:
“How much do I need for my goal, when do I need it, and how much can I sustainably invest?”
A basic goal-based process looks like:
Goal → Time available → Target amount → Suitable investment → Required contribution
For example:
Goal: Higher education fund
Time available: 12 years
Target: ₹15 lakh
The required investment can then be estimated using reasonable return assumptions while remembering that market returns aren’t guaranteed.
This is exactly why we’re building a MoneyTrendy SIP Calculator into the site.
Don’t Start a SIP Before Building Your Financial Base
Investing is important, but it shouldn’t automatically come before everything else.
Before committing substantial money to a market-linked SIP, consider whether you have:
Emergency savings
Unexpected expenses shouldn’t necessarily force you to redeem investments during an unfavourable market.
Essential insurance
Depending on your circumstances, appropriate health insurance—and life insurance where people financially depend on you—can be more urgent than increasing an SIP.
High-cost debt
If you’re paying very high interest on certain debt, evaluate whether addressing that liability deserves priority.
Sustainable monthly cash flow
Your SIP shouldn’t make normal household expenses difficult to manage.
This connects directly with our first MoneyTrendy article:
Savings Account vs Fixed Deposit: Where Should You Keep Your Money?
Your emergency and short-term money has a different job from money intended for long-term investment.
How Do You Choose a Mutual Fund for SIP?
This is where beginners need to be particularly careful.
Don’t select a mutual fund simply because:
- Someone on social media recommended it
- It recently produced the highest return
- A friend invested in it
- Its app shows an attractive star rating
- Its NAV looks “cheap”
- An advertisement promises exciting possibilities
Instead, begin with your goal and risk profile.
Understand the fund category
Broadly, mutual funds may invest in equity, debt or combinations of asset classes. Different categories can have very different risk characteristics.
Check the Riskometer
SEBI requires mutual fund schemes to display a Riskometer showing the scheme’s risk level.
The scale ranges from Low through Very High, helping investors understand the broad risk associated with a scheme.
Don’t ignore it.
A SIP into a very-high-risk scheme doesn’t become low risk simply because you’re investing monthly.
Understand the investment objective
Ask:
What does this fund actually invest in?
A mutual fund’s name alone shouldn’t determine your decision.
Look beyond recent returns
A fund that performed exceptionally over the last year isn’t guaranteed to repeat that performance.
Past performance isn’t a promise of future returns.
Direct Plan vs Regular Plan
When choosing a mutual fund, you’ll commonly encounter:
Direct Plan
and
Regular Plan
The underlying scheme portfolio is generally the same, but their cost structures differ.
SEBI explains that regular plans are purchased through intermediaries and include associated distribution costs, while direct plans don’t involve such intermediary commissions and therefore generally have lower expense ratios.
That doesn’t automatically mean every beginner should choose one route without considering their needs.
If you need personalised advice, understand what service you’re receiving and how the adviser or distributor is compensated.
If you’re making your own investment decisions, understand the direct-plan option and its costs.
Common SIP Mistakes Beginners Should Avoid
Treating SIP like a guaranteed-return product
It isn’t.
Your investment remains exposed to the risks of the selected mutual fund.
Starting without a financial goal
“Everyone is doing SIP” isn’t an investment strategy.
Know what you’re investing for.
Choosing funds only from past returns
Recent winners can become future laggards.
Understand the fund rather than chasing rankings.
Stopping the moment markets fall
A market decline doesn’t automatically mean your original investment plan was wrong.
Reassess the fund and your goal rather than reacting purely to fear.
Starting too many SIPs
Owning numerous mutual funds doesn’t automatically create better diversification.
You may simply end up holding overlapping investments.
Investing money you may need soon
Equity-oriented investments can fluctuate significantly.
Money needed in the near future may require a different home.
Increasing SIPs without checking affordability
Investment discipline shouldn’t turn into cash-flow stress.
What Is a Step-Up SIP?
As your income grows, you may be able to increase your SIP contribution.
For example:
Year 1: ₹3,000/month
Year 2: ₹3,500/month
Year 3: ₹4,000/month
Year 4: ₹4,500/month
This approach is often called a Step-Up SIP or Top-Up SIP.
It can help your investment contribution grow alongside your earning capacity.
You don’t necessarily need to begin with an intimidating amount.
Start with something sustainable and consider increasing it as your finances improve.
Should You Invest ₹500 per Month?
If ₹500 is what you can comfortably begin with, it can be a perfectly reasonable starting point where the selected scheme permits that minimum.
The more important habit is:
Start appropriately → remain consistent → increase when affordable → review periodically.
Don’t dismiss a small beginning.
But equally, don’t assume that ₹500 per month will automatically fund every large financial goal.
Your contribution needs to match the eventual goal.
When Might SIP Not Be Appropriate?
SIP isn’t automatically the solution for every financial objective.
You should reconsider a market-linked SIP when:
- You need the money very soon
- You don’t yet have adequate emergency liquidity
- You’re unable to tolerate fluctuations in the chosen investment
- You don’t understand what the fund invests in
- You’re investing solely because someone promised high returns
- Your selected scheme doesn’t match your goal or time horizon
The objective isn’t to have a SIP.
The objective is to use an appropriate investment strategy to reach a financial goal.
A Simple SIP Framework for Beginners
Before starting, answer these five questions:
1. What am I investing for?
Retirement? Education? A home? General long-term wealth?
2. When will I need the money?
Three years and twenty years require very different thinking.
3. How much risk can I actually tolerate?
Not how much risk you think you can tolerate when markets are rising.
How would you react if your investment temporarily fell 20%?
4. How much can I invest consistently?
Choose an amount that works with your real monthly budget.
5. Does the mutual fund fit the goal?
Understand its category, objective, costs and Riskometer before investing.
Only then should you set up the SIP.
SIP vs RD: Are They the Same?
No.
They may look similar because both can involve putting aside money regularly.
But the underlying products are fundamentally different.
| SIP in Mutual Fund | Bank RD |
|---|---|
| Investment method | Deposit product |
| Market-linked | Predetermined deposit interest |
| Returns not guaranteed | Return determined by deposit terms |
| Value can fluctuate | Generally much more predictable |
| Risk depends on mutual fund | Bank-deposit characteristics apply |
| Used for investing | Used primarily for systematic saving |
Don’t choose between them merely by asking which one “gives more return.”
First decide whether your goal calls for saving or market-linked investing.
Is SIP Safe?
The question needs to be reframed.
A SIP itself doesn’t have a single risk level because SIP is merely the method used to invest.
The risk comes primarily from the mutual fund scheme you choose.
A SIP in an equity fund and a SIP in a debt-oriented fund can have very different risk characteristics.
SEBI’s Riskometer exists specifically to help investors understand this distinction.
So instead of asking:
“Is SIP safe?”
ask:
“What does this mutual fund invest in, and what risks am I taking?”
That’s a much better investing question.
The MoneyTrendy Takeaway
A SIP isn’t a shortcut to becoming rich.
It doesn’t guarantee returns.
It doesn’t eliminate market risk.
And it doesn’t turn a poor investment choice into a good one.
What a SIP can do is make investing systematic.
You decide:
how much → where → how often → for what goal
and then continue investing according to that plan.
For beginners, the biggest advantage may therefore be behavioural rather than magical:
A SIP turns investing from something you intend to do into something you actually do regularly.
Start with the goal.
Understand the fund.
Choose an amount you can sustain.
And give the investment enough time to do the job you selected it for.
Frequently Asked Questions
What is the full form of SIP?
SIP stands for Systematic Investment Plan. It is a method of investing a fixed amount periodically into a mutual fund scheme.
Is ₹500 enough to start a SIP?
Some mutual fund SIPs permit investments starting at ₹500 per month, while AMFI also currently refers to ₹250 monthly Chhoti SIPs. Minimum amounts vary by scheme and facility, so check the current scheme terms before investing.
Can I lose money in SIP?
Yes. SIP investments in mutual funds are market-linked, and their value can fall. SIP does not guarantee profit or protect against losses.
Is SIP better than FD?
They serve different purposes. An FD is a deposit product with predetermined terms, whereas an SIP is a method of investing periodically in a mutual fund. The appropriate choice depends on your goal, time horizon, liquidity requirements and risk tolerance.
What happens if I miss an SIP?
The exact consequences depend on the mandate, AMC, scheme and platform arrangements. One failed instalment does not mean you should assume your entire mutual fund holding disappears; check the applicable SIP terms and mandate rules.
Can I stop a SIP?
SIPs can generally be cancelled according to the applicable AMC/platform process. Stopping future SIP instalments and redeeming existing mutual fund units are separate actions.
Does SIP guarantee 10%, 12% or 15% returns?
No. Mutual fund returns are market-linked. Numbers used in SIP calculators are assumptions for illustration, not guaranteed future returns.
Which SIP is best for beginners?
There is no universally “best SIP.” SIP is only an investment method. The appropriate mutual fund depends on your financial goal, investment horizon, risk tolerance and other circumstances.
Editorial & financial note
MoneyTrendy content is educational and does not constitute personalised financial, investment, tax or legal advice.